Showing posts with label account balances. Show all posts

Sunday, January 06, 2013

2012 Year-end Net Worth

There is a hidden benefit to my recent lax-ness about tracking my net worth-- after not having calculated it for a few months, it was really fun to see the number rise by about $50,000 all at once!
Here's the last few months I'd put into a spreadsheet-- nice jump from July to December!


Part of this is due to my lower monthly expenses now that I'm renting out my apartment. I also saw a nice bump from the increase in value of my investments, and a few thousand dollars worth of dividends that hit at the end of the year. I didn't hit my goal of $700,000, but I had thought that was pretty aggressive all along. Still, my net worth increased by over $100,000 from the end of 2011's net worth of $565,459-- this is the first time ever that my net worth has increased by six figures in a year. My salary and bonus came to just under $125,000, and I haven't been especially frugal lately, which just goes to show you how having money makes more money. The snowball effect!

More details to come soon on my expenses for the year...

Monday, November 07, 2011

Net Worth July-October 2011

Another belated net worth update. (I was trying to post updates on NetworthIQ but the site doesn't seem to be working and their security certificate is expired. What's up over there?)

Anyway, it's been an interesting few months-- some big ups and downs in my investment accounts. Mostly downs, unfortunately! After hitting a high of $591,390 back at the end of April, the stock market has been very cruel to me. I had a nice recovery in October, but I'm still down quite a bit from where I was.


Not much else of interest to report, other than moving a few thousand dollars from cash into mutual funds and some more I-Bonds at Treasury Direct. My credit card balance is in about the range it usually is, so no unusual levels of spending (and as always, I'm paying it in full every month). I've already maxed out my 401k deductions for the year, so any further changes in the retirement accounts will be due to investment gains and losses alone. At some point in the next few months I'll probably pay some extra principal on my mortgage and increase the home equity amount.

Stay tuned for a long overdue update on my spending and budget categories. Onward and upward!

Monday, October 17, 2011

Net Worth Jan-June 2011

I've been very bad about keeping up with my monthly updates, but here's some summary numbers I ran a while back looking at net worth shifts for the first half of this year:


I moved some cash into my investment account in March, which explains cash going down so much that month. (Though cash went down by less than investments went up because I also received my bonus that month.) My credit card balance is fairly consistent most months, except in March-- not sure what happened then, I don't remember being particularly frugal that month! (Just as a reminder, I do pay my credit card in full every month, but I count whatever's outstanding at the end of the month as a liability.) My overall net worth rose nicely over the 6 months, but you can see that May and June were tough, due to the stock market.
I'll be posting another update soon to bring things up to date for the 3rd quarter. It's not going to be pretty, I'm afraid. Back in April I was thinking I could hit $600k by the end of this year, but the market has been crazy and I don't think I'll even be close...

Tuesday, April 13, 2010

Mint Adds Manual Transactions

Mint.com has added a feature many people wanted: the ability to enter cash transactions and manually enter future transactions in other accounts. But the way it works is a little weird.

Let's look first at adding manual transactions, for instance to a checking account. This makes a lot of sense, as you really need to know what pending transactions could affect your account balance. You can enter a future check with a check number and later, when that check has actually cleared against your bank account, it will be automatically reconciled so you don't have a duplicate entry. I'm not sure how this would work with a savings account where there's no check number to help with matching the transactions.

As for cash transactions, I don't like the way they've implemented this. You can add a random transaction that isn't counted against any account if you just want to track cash expenses against a budget, but there's no way to maintain a cash account and enter expenses against it. Instead, they want you to assign your cash transactions to your recent ATM transactions, which some people were using as a workaround already. I guess they've made it a little easier to do that, but they've missed half the point of bothering to track cash in the first place. Cash is cash, and what matters is the total you have and the total you spend-- why would you need to assign it to a particular ATM transaction? And what if you receive payment in cash and then spend that money?

Another thing worth noting is that you can't yet enter new transactions from the iPhone app, which is really a necessity. Mint says they're working on adding that soon, though.

You can read more about this all works at the Mint Blog. Some of the comments bring up these exact issues so perhaps they'll listen to their users and make some changes.

But on the positive side, after using Mint for a couple of months now, I have to say that there is a lot to like about it. It's very easy to set up and I love being able to check my balances and see transactions on my iPhone. That makes it all the more frustrating that they have left a lot of good features out-- I wish I could see how the individual stocks and mutual funds in my portfolios were doing on my iPhone (showing how much they were up or down, not just the current price), rather than just a total balance. I wish the budgeting categories were a little more flexible. And the cash transaction thing is just bizarre. Let's hope they keep refining this without heading off in the wrong direction...

Friday, May 22, 2009

Feeling Flush

I'm not sure why, but I've built up quite a cushion in my Chase savings account-- just over $12,000 as I'm writing this. This is despite having made an extra mortgage payment of $2,000 just recently, and some transfers to other accounts. I use this Chase account to receive my direct deposit pay, and transfer money into my checking account to pay bills. I wondered if I'd made a mistake and forgotten to pay a bill, but apparently I'm all caught up!
The problem is that this cash is barely earning any interest. I think it's time to start shopping for some mutual funds again, and also transfer some money to my other savings account at FNBO, which earns more interest. I suppose I could also make another additional principal payment on my mortgage. In any case, not being able to decide what to do with over $10,000 is a nice problem to have!

Tuesday, September 30, 2008

The Hit

My 401k lost about $12,000 yesterday, and is now down almost 23% year to date. I was obviously not the only one checking this morning, as the website was very slow, and I got a message at one point that the system was unavailable!
My E*Trade account is down about 18.5% YTD, and my E*Trade Roth IRA is down about 14.5% YTD. Yesterday's drop didn't seem to hit as hard on E*Trade, but I have a lot less money there anyway.
Did you check your investment accounts today? How did yesterday affect you?

Thursday, September 25, 2008

My Fat Wallet

Today is one of those rare occasions when my wallet is stuffed with cash, including a $100 bill and a $50 bill. I had dinner with some friends last night, including one who was visiting from the UK and had exchanged money for a lot of US currency. Everyone at the dinner wanted to pay cash except me-- I was happy to put the whole thing on my credit card and earn some frequent flier miles. I had gone to an ATM fairly recently, so now I have this big wad of money, coming to $381!
Sometimes I feel a little nervous carrying so much cash-- I mean, what if I get mugged? But then I think, well, I wouldn't want to be mugged no matter how much money I was carrying. It would be a shame to lose a large amount of money, but maybe if I could give the mugger a lot of cash, they'd be more inclined to just take it and run rather than beating me up, or worse!
How much cash is in your wallet today?

Thursday, June 26, 2008

Once Upon a Time...

... there was a little fairy princess named Madame X. Okay, she wasn't really a fairy princess, but she lived a long time ago and far away. And okay, I'm only talking about 16 years ago and a few hundred miles, but sometimes I look back at my younger self and feel as though she is some strange creature out of a story!

I was going through some old notebooks again, and found a page of financial notes, the beginnings of which seem to date to 1992. I was living with my parents at the time, and looking for my first apartment of my own in Boston. Here's what I wrote:

----- rent $850 tops if no T pass
540 exp or 510 if no T pass
$800 if T pass needed

also account for utilities
if included
figure $600 expenses + RENT

GOAL: 7/17/92
bank balance ~4250
by 6/1/93
target bank balance $11,500
if no bonus
$14,000
if bonus
~ adjust for 401k?

ALSO:
DONATE $100/yr to charity.

actual 6/1/93 approx $4,000!
6/95 approx $6,000
3/96 $13,000+
-- apt. down payment

7/97 $8,800

10/97 pd off $3,000 student loan

10/97 appr. $5500 savings + [$2000 CD]
On another page of the notebook, I'd written this:
4-15-94
Bank Balance-- checking 4971.90
savings 2650.00
total $7521.90

401k + pensi0n -- ?

Goal: $10,000 in savings by next April

April 95-- have about 6000 checking and savings comb.

3/96-- $13,000-$14,000

7/97- $8800
Obviously I am now a lot better at keeping financial records and at setting realistic goals! But still, it's neat to look back and see that even then, I was managing to slightly increase my net worth. I can't believe I set myself a budget of $850 maximum for an apartment, though: my salary at the time was about $19,000, though at about that time in 1992 I may have just gotten a promotion that brought it up to $30,000. Either way, the apartment I ended up renting only cost me $600 a month and I still found it tough to save.

It's also interesting to think about how much my life changed within the first 6 or 7 years after getting out of college. I went from being someone who was unemployed with a couple thousand dollars of credit card debt to someone who was making $19k and had a few thousand dollars in the bank, to someone who was living in NYC, making over $30k and had a few thousand dollars plus some unknown amount in a 401k, to someone who was making about $45,000, had $8,800 in the bank, co-owned her first home, and had paid off her student loans a few years early.

Add another 10 years to the calendar, and I'd become someone who was making just under 6 figures, owned her own condo, had traveled to 7 or 8 more countries, spoke two more languages, had loved and lost and loved again, and had a variety of bank accounts and investments generating a net worth of around $350,000.

It does kind of sound like a fairy tale, doesn't it?

Monday, November 05, 2007

October Net Worth

Ok, time to do the monthly numbers again. Quicken tells me that my net worth on Oct. 31st was $365,383, an increase of 2.6%. This is excitingly close to my year-end goal, however, it's a bit suspect as when I was looking at it the other day, my 401k showed a higher balance in the net worth report than it did in another screen. Anyway, for now, I'll take it. It makes me feel a little better given how much lower it is today after the recent stock market slump.
A commenter asked me to explain the composition of my net worth in more detail, so here is the full scoop:

Cash & Bank Accounts:

  • Cash $37
  • Chase CD 6 mo. to 3/08 $3,034 @ 3.92%
  • Chase Checking $160 @ negligible interest rate
  • Chase Roth IRA CD 48 month to 4/09 $3,020 @ 4.16%
  • Chase Roth IRA CD 60 month to 2/09 $2,627 @ 3.25%
  • Chase Savings $3,400 @ 0.8%
  • E*Trade 2-Yr CD to 10/08 $5,899 @ interest rate 4.75%?? hard to tell, for some reason E*Trade is making it very difficult to see what my actual interest rate is! But it must be in that range given what my recent quarterly interest payment was (see Rule 17 about doing the math).
  • E*Trade Money Market $5,001 @ 2.5%. I will leave this here for a couple of months, probably, but I plan to close this account soon and invest the money elsewhere. This may result in my being charge a higher fee per trade in my E*Trade brokerage account, but I hardly ever do any trades, so no great loss.
  • FNBO Direct Savings $11,000 @ 5.05%
  • Laundry Quarters $7

Investments:

  • E*Trade $18,142 Return on this portfolio was 11.7% in 2006
  • E*Trade Roth IRA $24,813 Return on this portfolio was 7.69% in 2006
  • 401k $202,314 Return on this portfolio was 11.5% in 2006
  • Treasury Direct & Bonds $4,482 This is all I-bonds, rates 3.63-4.18%

Other:
  • Credit card balance -$2,646
  • Home Equity $84,059

So that means about 60% of my total net worth is in stocks & mutual funds earning 7-11% last year, 17% of my net worth is earning in the 3-5% range or less, and 23% is home equity. If you look at it just in terms of my investable assets, about 77% is in stocks and mutual funds, and 23% is in cash/CDs/bonds, etc. At my age, I suppose I could nudge myself a little further into risky investments like stocks, but not too much further. I like knowing that I have secure, steady investments balancing things out-- but I do need to make sure I pay attention when my CDs mature to make sure I get the best rates available, and also watch my bank accounts to make sure I am maximizing my interest there too. I did some work on that this month, by opening the FNBO Direct account with money I'd had in the E*Trade money market account.

Tuesday, July 10, 2007

Early Signs of a PF Blogger in the Making

As I continue to refine how my stuff is organized in my (relatively) new home, and put away stuff from those last couple of boxes, I've been digging into some more old notebooks. I found one that I didn't remember keeping at all-- I started it on January 1st, the year after I graduated from college. I guess I had made it a New Year's resolution to record "each day's spending, bank balances, the weather, what I did/read, who I called, mail received or sent and Things To Do."
Here is the first day's entry:

Jan 1st
CBT bal. -- [nothing actually recorded]
B. of B. bal.-- $16.81
Cash on hand-- $31 bills, $3.96 coin = $34.96
$350 in checks to be deposited
Visa debt [nothing recorded]
Other debts-- A.-- bills?
$ owed to me-- C: 4 months phone, K: 2 mo,? A: phone?
$ spent today-- $0.00
cold and sunny
went to G's house
called Kathy
A. called
finished A Place I've Never Been


The next few days record similar items. I read Beloved, took my grandmother and great-aunt to the mall, went to a movie with a friend, noted that I was worried about the economy and that one of my banks was owned by a larger bank that had just gone bankrupt. I also wrote some notes about completely ridiculous made-up things that my old roommates were supposedly doing after graduation, which I later managed to get printed in the alumni magazine-- I guess no one thought it was a stretch that a certain person would have quit her banking job to play a Teenage Mutant Ninja Turtle in the Icecapades.

After the holidays, I went back to work at my 2 day a week job. Most of my meals seem to have been bought at WaWa's & McDonalds. On January 14th I had an interview for an internship. On Jan. 23rd I wrote "Financially, I am f***ed." In February, I paid $35 to take the GRE.
Also in February, I noted that I had been to a party that was "fabulous, but somehow, things turned shitty. Felt very ill in the morning." I also apparently got an obscene phone call that I must have reported to the police as complaint #13898. I don't remember that at all.
The only things I seemed to spend money on besides food and rent were newspapers, an occasional book, art supplies and too-frequent trips to the used record store.

What is weird is that I was running up a balance on my credit card but I never seemed to note how much the total was, only that I was often paying a $10 minimum towards it. I also had to start paying back my student loans around then, at a minimum of $98 a month.

Sometime in March, I wrote this entry, in red ink on one of the last pages of the notebook:
I DON'T HAVE ENOUGH MONEY TO PAY MY RENT. I WILL NOT HAVE ANY MONEY TO MAKE MY NEXT LOAN PAYMENT. I CAN'T PAY MY VISA BILL.
I CAN'T GO TO FLORIDA.
I NEED A LOAN FROM MOM AND DAD.
A. OWES ME $10
bal. $144.50
must pay Visa minimum $10? $20?
must pay rent $260
will get $177.44 next paycheck
no more cash until after break

I'll have to go through some more notebooks to see if I continued to track my finances the rest of that spring, but it will come as no surprise that in early June of that year, I moved back in with my parents and tried to start over. Within a couple of months, I had a full-time job. Within a couple of years, I was renting my own apartment, and money was tight again, but it was never as bad as it had been in that notebook.
I remember being so depressed about it, and feeling like I would never get my life together. I never felt truly desperate, as I knew my parents would help me out up to a point, but I found it incredibly humiliating to have to ask. It made me feel like a complete failure, which I suppose was me being a little hard on myself, as I was all of 22. But college was over, and I wanted life to begin: life as in "making a living." It's strange to look back and realize that I now have pretty much everything I ever wanted back then.

Tuesday, May 15, 2007

Back to Normal

Yes, I'm back... it feels like I've been away from regular life for a while-- work trips, vacation, and the herculean task of hosting the Carnival of Personal Finance. (Actually it wasn't all that bad... you should try it sometime!)
So since I'm back in it, what IS regular life, anyway? At least financially speaking? I was thinking about what my usual routines are:

Daily:
I enter my cash transactions in Pocket Quicken, on my Treo. This tends to be for breakfast and lunch, and not much else. I also check my main savings and checking account balances online most days, just to make sure there aren't any auto-payments I've forgotten to cover, or weird charges on my credit card, which happens to be with the same bank, so it's all in one website.
Then of course there is all my daily reading: the New York Times on the way to work, and various blogs and websites I tend to check up on, on finance and real estate topics.
For most days, that is it as far as finance-related activities go. Occasionally I will also do a little shopping at lunchtime, or while sitting at my computer. And some days I buy groceries on the way home, or maybe have dinner out with a friend. But otherwise I don't spend much money.

Weekly:
Once or maybe twice a week, I synchronize my Pocket Quicken transactions with the desktop version on my Mac. At the same time, I download all the latest security prices for my portfolio, and also download recent credit card transactions.
On Fridays, I also update a spreadsheet I've been keeping that tracks the number of real estate listings in the NY Times, for a little experiment of mine that I posted about a while back.
I used to check my E*Trade account at least weekly, but lately I don't bother. I can see the overall balance update in Quicken, and other than that I have been feeling pretty hands-off about it lately.
Another weekly activity of late is a lot of household errand-running on the weekends: this is when I spend money! Though the decorating of my new condo is winding down a bit, the change of seasons has gotten me into gardening. I'll post more later about my newly-green thumb and how much it's costing me.

Twice a month:
I enter all my salary and deductions from my paystub into Quicken.

Monthly:
About once or maybe twice a month, I pay my bills, and set up transfers between savings and checking to cover them. Some bills and transfers are set up for auto-payment, so it's just a question of making sure they're entered in Quicken. For others, I have to go over the bills and manually enter the amounts for electronic payment, or for my condo maintenance, a paper check. I also reconcile my savings and checking transactions in Quicken using my bank statement, enter investment account transactions from my 401k and E*Trade statements, and check off all my credit card receipts against the statement, then stapling them to it and filing it.
"Filing" means just shoving these papers into a bin for a while!
I try to get all the statements entered within the first week of the month, so I can post an accurate net worth on this site. Each month, I also use the category summary report in Quicken to update a spreadsheet that I keep which tracks how much of my net paycheck I'm actually saving-- even though I plow a lot of money into my 401k through deductions, I like to track how I'm doing against my budget for saving cash on top of that.

Quarterly:
That bin I've "filed" papers in starts to get full, so I go through it, weed out unneeded items, and try to fit everything else into an actual filing cabinet where I keep my tax returns, credit card statements, etc. I used to keep bank statements for quite a while too, but now that they are available online and I have the data in Quicken, I throw them out within a year.

Yearly:
I pull together all my tax-related paperwork and go over all my expenses for tax deductible items. Since I've kept things fairly organized throughout the year, this isn't too onerous a task. And at the beginning of each year, I look at all my spending, savings, investment performance, net worth growth and goals for the following year-- and blog about them here, of course!

These are the basic ways I keep track of my financial life-- I like to stay aware of where I'm at, and not let the paperwork pile up til it gets overwhelming. Sometimes it seems like I spend a lot of time on it, but really it's probably only a few hours a month at most. It just seems like more to me because I am always thinking and blogging about it!

What are your financial routines? How do you stay organized?

Tuesday, February 13, 2007

$310.24

That is how much money I have in my savings account right now-- the lowest it's been in as long as I can remember. Of course this is just my everyday savings account-- my paycheck is deposited here, and I transfer money from this account to my checking account to pay bills, and move money from it to other savings accounts when I think there is enough of a cushion. I recently set up an automatic transfer of $225 a month from this account to my E*Trade Money Market account, which earns more interest. That $225 is what I would like to force myself to save every month, but lately, with all the money I've been spending on my apartment, I'm actually not saving any money.
I have about $17,400 in the E*Trade account. That is my only other liquid cash, but it's enough to live on for a few months if needed. I recently moved $4,000 out of that account to make my 2006 Roth IRA contribution. I don't think of any particular part of my savings as an "Emergency Fund." Perhaps I should, but my view is that in a true emergency, you just do what you have to do. I do like keeping enough cash around to tide me over for a while, but if I were really desperate, I'd sell some mutual funds, or at worst, cash in a CD or dip into my retirement funds a little.
I feel very fortunate to have these options, but it's still a funny feeling to see a 3-figure balance in that savings account. In a few days, I'll get paid, but a good chunk of that paycheck will go to my mortgage. The next paycheck after that will give me a little more breathing room, but soon after that I'll have another credit card bill due, and if I've managed to buy a bed by then, I'll be temporarily wiped out again, and will have to transfer some savings back from my E*Trade stash. I'll probably have a hard time catching up until I get my bonus sometime in late March or early April.
It's been a long time since I lived paycheck-to-paycheck-- when I did, I got through it by running up a couple thousand dollars in credit card debt, which I was able to pay off quickly by moving back in with my parents for a year or so. Even then, I was lucky enough to have another sort of safety net. I'm not really living paycheck-to-paycheck now, but trying to pretend I am is a good way to give myself a reality check about how much money I'm spending.

Friday, February 02, 2007

I've Got Cash?!?

I happened to be checking on my Feedburner stats and got a pleasant surprise-- I've actually been getting some ad payments from Feedburner Ad Network every month! The thing is, they send them to me via PayPal, which I hardly ever use anymore, ever since I got over my addiction to buying and selling PDAs on EBay! And I guess they don't send you a little email any more to tell you you've got cash, probably hoping for exactly what happened with me, which was that I left the money sitting there and didn't withdraw it! At least it's earning interest. I guess I should start thinking of PayPal as an account and set it up in Quicken, so I can include any balances in my net worth. It's not a huge amount of money (I'd tell you how much but I imagine it's against their policies), but it was a nice thing to stumble across.

Wednesday, May 17, 2006

Rule #13: Know Thyself

Here's a "back to basics" rule that always comes in handy!
I think one of the most important keys to managing your finances is to be aware of what you are really spending money on. Think about it-- whenever people complain about being broke, don't they always say something along the lines of "I swear, I just don't know where it all goes!"

There are so many things about money that are unknowable and unpredictable. You can strategize and make educated guesses, but no one really knows what the performance of an investment will be, where interest rates will go, how tax laws will change, or whether they'll get a raise. But one thing you CAN know is what your own spending and savings habits are, and for most people, it's probably a pretty good starting place to figure out what they will be in the future, or how best to change them. Once you know what is knowable, then you can worry about the guesswork. First of all:

  • Keep Records
First of all, make sure you are saving all your credit card bills and bank statements. You should be doing that anyway! That's the easy part. What's harder is to start tracking how much cash you spend. Keep a little notebook, or jot things on your daily planner or in a PDA. (I enter every penny of cash I spend into Pocket Quicken on my Palm, and then upload the transactions to the desktop version of Quicken, where I enter or download all my other credit card and bank transactions.) Even if you sometimes forget, just do it whenever you think of it. You'll start to realize that you probably spend cash on the same things quite often, so you'll start to see patterns. For every dollar you jot down, that's one less dollar whose disappearance will be a mystery later. Once you have these records of what you have spent,
  • Look at your spending records and total them up by category.

I think a software program such as Quicken is a great investment, but you can also easily create an Excel spreadsheet or two that will serve the same purpose. Before I had Quicken, I used to do a big spreadsheet once a year. I'd sit down with my bank statements and credit card bills and enter all the transactions and sort them into broad categories. For checks and credit card expenses, it was easy to see what I had spent the money on. For cash, it was harder, but I totalled up all my ATM withdrawals and then thought about all the things I tended to buy with cash-- I multiplied out what I tended to spend on breakfast and lunch and subtracted those from the total. I subtracted an amount for laundry. Whatever was left was just categorized as miscellaneous. It wasn't very accurate, but it was a start.
Think about the categories your expenses fall into-- which ones are fixed expenses, such as a mortgage payment. Which ones are variable expenses, such as clothing? Which ones are necessities and which ones are luxuries? There is no one right way to do this-- think about what makes sense for you. Instead of just having a category for Books, for instance, you might want to have a category for Education and another for Entertainment. The cost of a book about how to start your own business might be put under Education, but a Danielle Steele novel would go under Entertainment-- you might want to think about what expenses are investments in your future in some way, vs. just throwaway spending on something with only temporary value.
  • Analyze the data
Once you have a system for collecting the data and sorting it into categories, look at it! Think about it! Play with it! You may be surprised at what you learn. Maybe you didn't realize you were spending just as much on buying lunch every day as you were on clothes. Maybe you didn't realize your cable TV bill was 5% of your take-home pay. Maybe you didn't realize you'd forgotten to include an awful lot of things when you came up with that supposed budget you were going to follow.
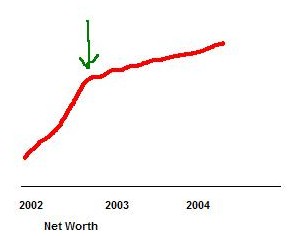
This is where Quicken can make things really fun, because of all the reports and graphs you can easily run. For example, a few years ago, I started hanging out with some new friends I'd made, who happened to enjoy good food more than some of my other friends, who I also didn't see as often. Here's a rough illustration of what I discovered:

The green arrow represents when I met those new friends, changed my social habits and started eating dinner out more often and more expensively. The shape of the red line representing my net worth is a bit exaggerated, but it just blew my mind how noticeable it was that I was saving less money just because I had started hanging out with different people! So you can bet I dropped them like a hot potato!
Ok, I'm kidding-- I did not really sacrifice my friendships on the altar of personal finance, but it did make me think we should maybe start doing some at-home dinner parties more often instead of blowing so much money at restaurants!
For other people, graphing net worth vs. friendships might be irrelevant, but if you can look at how your spending changes throughout the year, how much you spend in different categories, whether you're saving money each month or constantly in the red, you're bound to learn something about yourself. (And though analyzing your spending is a good place to start, don't forget to look at your income and investments too.) In the long run, that awareness will help you make decisions and align your actions with your priorities and goals, whatever they may be.

I suppose the reason I decided to post about this today is that I am so stressed out about what's going on with my condo purchase! I keep thinking about how much it's going to cost and trying to figure out the long-term consequences of my decisions. Sometimes it feels like I've bitten off more than I can chew, but then I remind myself that I know what I spend. I know what I have to spend and what I can cut. I know how much I save. I know where my limits are. I can do this. I'll be okay.

Tuesday, January 10, 2006

My Wallet is Open, Really!

Given the title of my blog, today I thought I would tell you what is in my open wallet, literally.

$2.02

And happily, this matches the balance in my Quicken cash account exactly. I usually carry more cash around than this, but I haven't had a chance to go to the ATM in the last few days. I usually take out $100 at a time, whenever I think I might need it, or when my cash on hand gets around $40 or less. The only things I tend to spend cash on are breakfast and lunch, so I can often go awhile without taking out money. Since I've been cutting back on my breakfast and lunch expenses, it's noticeable how much less often I visit the ATM. But over the weekend I went out to a couple of bars and paid cash for drinks, so now I am running low.

I am always fascinated when I notice people paying cash and peeling the bills off of gigantic wads of money. I know a lot of people just cash their paychecks and carry the money around until they spend it. But other people just feel nervous without a lot of money in their pockets, I think. My uncle is a case in point. He makes plenty of money and certainly keeps it in the bank, but he always seems to have several hundred dollars in cash in his wallet. He also just likes to pay for a lot of things in cash rather than using credit cards. Even though he drives everywhere and pays lots of tolls, he refuses to use an EZPass because he doesn't want the government to be able to track his movements. Well, strange paranoias aside, I wonder how others feel about this issue. What do you spend cash on? How much of it do you carry around? Please chime in and vote in the poll below!


How much cash do you usually carry in your wallet?
$1-$20
$21-$50
$51-$100
$101-$300
Over $300


Free polls from Pollhost.com